Tuesday, July 30, 2013

Great Recession Cost United States Up to $14 Trillion

To those apologists that claim that the megabanks have repaid their TARP loans, thus no harm no foul for the egregious bubble behavior that precipitated the mortgage crisis, the Dallas Fed has just released a report that estimates that the crisis will end up costing the U.S. between $6 trillion and $14 trillion in lost economic output.  According to economists Tyler Atkinson, David Luttrell, and Harvey Rosenblum, the study estimates the difference between actual and projected economic growth and the growth that likely would have occurred had the crisis never taken place.  These economists called their estimate "conservative," noting that quantifying the trauma of job loss, rising unemployment, and the "burden of unemployment" likely makes their estimate a "drastic understatement" of the cost of the crisis.

In addition, Barron's reports that the "second great contraction" in the U.S. strained the federal government's resources and capabilities by adding to the level of government debt. . . .  "Some critics of big banks, such as the Massachusetts Institute of Technology’s Simon Johnson, have argued that the lost output and tax revenues caused by the financial crisis strengthen the case for stricter regulation of banking.  Richard Fisher, the president of the Dallas Fed, is a prominent critic of too-big-to-fail banks and has called for Wall Street’s biggest banks to be broken up."


From the report:  "The “Second Great Contraction ”in the U.S. was the result of a confl‡uence of factors: bad loans made by banks, ratings agencies falling down on the job, lax regulatory policies, misguided government incentives that encouraged banks to be reckless in their lending, and even monetary policy that kept interest rates too low for too long.

The Second Great Contraction, the worst economic downturn since the 1930s, was unusual because it stemmed from an easing of credit standards and an abundance of …financing that had fueled the prior expansion. This fuel also helped create imbalances— an overextension of mortgage …financing and capital market fi…nancial intermediation. A housing collapse and credit shocks, culminating in a fi…nancial crisis, hit the economy as these fi…nancial practices generated new losses. Home construction plunged, the stock market crashed, commodity prices tumbled, job losses mounted, credit standards tightened, and short-term funding markets seized up."

The culmination of this morass is lost economic output between $6 and $14 trillion dollars.  Indeed, repaying TARP loans appears to only be the tip of the iceberg that the Wall Street banks owe the citizens of this nation as far as restitution and penitence is concerned.

Friday, July 26, 2013

Megabankers Face a 10 Year Statute of Limitations

This blog has consistently urged more accountability for financial elites at the megabanks. While the Obama administration clearly gets a failing grade for enforcing criminal statutes against those at the megabanks, another Attorney General or administration can still bring criminal charges so long as the statute of limitations has not expired. This would be a first step in restoring the rule of law to the financial sector and stemming the most egregious element of lawless capitalism. So what is the statute of limitations applicable to bank frauds and other crimes affecting a financial institution?

Under 18 U.S.C.§ 3293 the limitations period for criminal charges for bank fraud as well as wire fraud and mail fraud that "affects a financial institution" is 10 years. This is twice as long as the five year statute that generally provides the limitations period for federal offenses and four years longer than the limitations period applicable to securities violations and commodities fraud. The definition of a "financial institution" includes any insured depository institution and any holding company of any insured depository institution. Further, federal frauds may involve schemes that continue beyond the fraudulent mailing or transmission that effectively will extend that period to 10 years after the scheme has ended. Moreover, under United States v. Pelullo, 964 F.2d 193 (3d Cir. 1992), frauds affecting a subsidiary of a financial institution "affect a financial institution." By the same logic, any loss to any subsidiary of a holding company also will "affect a financial institution." Finally, any fraud committed within a financial institution clearly "affects a financial institution" and is subject to the 10 year statute of limitations because it exposes the financial institution to an increased risk of loss.

Interestingly, Congress added the term "mortgage lending business" to the definition of financial institution under 18 U.S.C.§ 20 as part of the Fraud Enforcement Recovery Act of 2009. "Congress, of course, has the power to extend the period of limitations without running afoul of the ex post facto clause, provided the [original] period has not already run.” United States v. Madia, 955 F.2d 538 (8th Cir.1992). In general, statutes of limitation are deemed procedural and are applicable to claims brought after the enactment of the statute. Thus, any criminal charges relating to a "mortgage lending business" brought after May 20, 2009 are subject to the new 10 year statute of limitations so long as not already time-barred as of that date.

What does all this mean? It means that virtually all of the putative criminal conduct at the megabanks arising from the crisis of 2007-2009 is not time-barred until 2017 at the earliest.

 For example, consider the misconduct of Angelo Mozilo, the former CEO of Countrywide. The SEC charged Mozilo with securities fraud in a civil action. On the eve of trial the case settled for nearly $70 million. The SEC charged Mozilo with securities fraud in connection with his sale of almost $140 million of Countrywide securities between November of 2006 and August of 2007. Shortly thereafter Countrywide drowned in an ocean of subprime loan defaults and its stock price plunged. The SEC alleged that Mozilo knew of the problems with the quality of Countrywide subprime loans when he sold his shares even though Countrywide shareholders had no clue. Mozilo agreed to the largest fine ever for a pubic company's senior executive to settle with the SEC. As the Supreme Court recently ruled, the SEC would be subject to a five year statute of limitations for this kind of claim. If the DOJ picked up on the investigation of the SEC and pursued a criminal securities fraud actions, then the general criminal statute of limitations (18 U.S.C.§ 3282)
of five years would apply.

But there would be at least four possible bases for applying the 10 year statute of limitations to Mozilo for the very same factual allegations that the SEC made against Mozilo: 1) his misconduct affected a mortgage lending business; 2) his misconduct caused losses to any financial institution that held shares in Countrywide; 3) his misconduct caused a risk of loss to Countrywide Bank FSB or its holding company; 4) his misconduct caused losses to financial institutions that relied on the same misrepresentations Countrywide made to shareholders regarding the safety and soundness of its underwriting of home loans.

Of course, there has been no finding by any jury yet that Mozilo violated any criminal law. The only point here is that based upon what we now know about Mozilo and Countrywide, it is highly unlikely that any criminal indictment against Mozilo would be time-barred before 2017, more than four years from now.

The same holds true for Goldman Sachs, Citigroup, JP Morgan Chase, Lehman Brothers and Bank of America. Each of these entities is either a "financial institution" or is affiliated with a "financial institution" or dealt with a financial institution fraudulently according to SEC investigations underlying civil settlements (or, in the case of Lehman Brothers a bankruptcy investigation).

AIG also was affiliated with financial institution. As an insurance company there is another 10 year federal statute of limitations applicable to criminality by AIG's senior officers and directors. So, consider Joe Cassano's now infamous statement in August 2007: "It is hard for us, without being flippant, to even see a scenario within any kind of realm of reason that would see us losing one dollar in any of those transactions." One year later AIG posted the largest loss ever in corporate history from "those" credit default swap transactions. If this statement defrauded even one financial institution then the statute of limitations for any such fraud will not expire before August 2017.

The bottom line is that the overwhelming majority of potential criminal charges against the megabankers (as individuals) will not expire until 2017 at earliest. This means that WE THE PEOPLE have two elections ahead to elect responsible leaders that understand the importance of the rule of law and imposing accountability on even the most powerful economic actors. Indeed, perhaps Congress could even extend the statute of limitations to 15 years.
.

Monday, July 22, 2013

The Great Derivatives Scam

FRED GraphIt is hard to overstate the impact of megabank derivatives trading on our economy. Although three years after Dodd-Frank they remain a virtually dark market, experts estimate that the derivatives market may now exceed $1.2 quadrillion. A Quadrillion has 15 zeros and looks like this: 1,000,000,000,000,000.

Another way of thinking about that huge number is that it amounts to 20 times the entire global economy. While that huge number is only the notional amount it still represents a huge commitment of the world's capital resources--perhaps as much as $10 to $20 trillion dollars. All this capital is committed to an enormous zero sum game that carries an enormous risk of blowing up the financial system as occurred in 2008. As Michael Sivy points out, even a small move either way in the value of the huge notional amount of derivatives would wipe-out even well-capitalized banks. The size of the market necessarily implies huge problems and risks.

First, I contend that much of the so-called "money printing" of the Federal Reserve is dedicated to to derivatives trading with nearly zero resulting credit expansion at the megabanks. Second, much of the trading is the direct result of accounting fraud--specifically the accounting rules allow both counterparties to the same trade to recognize gains and this allows the megabanks to pump up their earnings accordingly. Third, a huge percentage of the trading occurs only because the megabanks can sell their too big to fail status to counterparties which in turn encourages more risk throughout the economy. Fourth, derivatives trading is heavily subsidized by depositors who now stand behind derivatives counterparties if a megabank fails. Thus, the next financial crisis will demonstrate that derivatives still pose a lethal risk to the global economy.


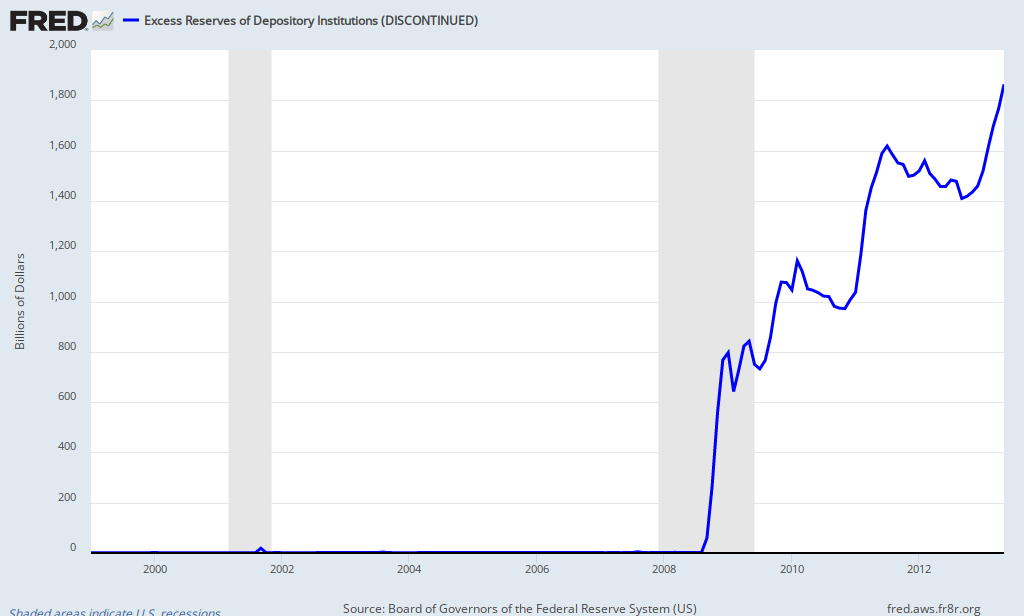
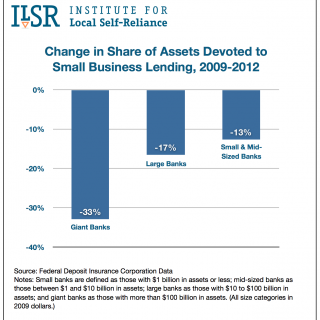
1) Fed and monetary policy. As demonstrated by the above chart, the monetary transmission is  and has been broken. Banks are not lending. Everyone agrees that if bank lending proceeded apace the economy would be expanding. Instead the banking system hoards excess reserves that could be lent out. In the wake of the crisis, the megabanks cut small business loans lending at more than twice the rate of community banks, as reflected in the chart in the chart at right. Thus, despite massive excess reserve to lend, bank lending still has not recovered to the pre-crisis. On the other hand, excess reserves held at the Fed are an ideal form of collateral for derivatives transactions, as my friend Christian Johnson explains, here at p. 9. And, since the Fed pays interest on excess reserves of .25 percent (well over the market rate for short term Treasuries with high liquidity of essentially zero percent), the Fed is basically subsidizing the megabanks' collateral on derivatives to the tune of billions of dollars per annum. The precise extent of this subsidy is unknowable; but the total subsidy to all commercial banks totals $5 billion per annum (.0025 times $2 trillion in reserves). While the exact numbers are difficult to pin down it is obvious that derivative trading is squeezing out lending and the Fed facilitates this activity through its payment of above market interest rates for banks holding excess reserves. In fact, trading profits are the key driver of megabank earnings as evident here, here, here and here. Simply put huge amounts of derivatives trading are squeezing out lending at the cost of economic growth.

2) Derivatives and Accounting Manipulation. The megabanks hold a total of about $210 trillion dollars in derivatives, nearly all of which are not traded on transparent exchanges but instead are traded over the counter (OTC). Zero Hedge recently posted an illuminating blog entry on the business of derivatives trading and profit manipulation at the banks. According to Zero Hedge Bank of America's entire profit would have been wiped out under mark-to-market accounting. All of the bank's profit resulted from the mark-to-model accounting method permitted since 2009 when the FASB promulgated Staff Position 157-4. Trading of complex derivatives has always involved a subjective determination of "fair value." So subjective that both parties to a derivatives transaction can, in fact, claim profits on the same derivative transaction. In fact, after Lehman's bankruptcy collateral apparently was wildly up for grabs due to the vagaries of valuing derivatives positions. All of this means that while derivatives are technically a zero-sum game (negative sum when substantial transactions costs are included) the megabanks still profit mightily in this market because of imperfect accounting. Where else can two parties to a bi-lateral contract both claim profits?

3) Selling TBTF Status and Government Guarantees. The derivatives markets allows the megabanks to sell the full faith and credit of the US government. Indeed, one may wonder how much of the market would exist without the ability to sell government guarantees. After all, the main reason in favor of derivatives transactions is that allows the free flow of risk to those best able to bear it and those who desire it. There is little doubt that TBTF lives as argued on this blog on the date Dodd-Frank was signed-- the only question is the size of the subsidy (a question the FDIC recently tackled in this literature review). So the megabanks offer the ideal mechanism to shift risks: a default proof counterparty. This is why the top five megabanks control 95% of the derivatives market. Every derivatives counterparty wants a default proof counterparty. Further, the megabanks will under-price this government guarantee since they bear virtually no prospective cost of the guarantee at all. The corollary to this is that the entire economy takes on too much risk because the megabanks are in business to sell government guarantees to all buyers, and the banks will assume concentrated risk such as the JP Morgan London Whale trade that cost the megabank billions. This high risk trading can be more nefarious than initially appears. Perhaps the best proof of my point is the behavior of the megabanks themselves: when they suffered ratings downgrades they moved much of their derivatives business to their bank subsidiaries so that the trading would be backed by insured deposits.

4) The Death of Depositor Preference. After the Great Depression even governing elites accepted that bank runs constituted a lethal risk to capitalism. Sustainable credit is a key prop to growth. Yet, credit cannot expand to maximum sustainable levels without fractional reserve banking. If a community panics and runs on a bank then the bank must face failure or need to raise cash by pulling lines of credit and calling loans. The answer to this risk is deposit insurance. The FDIC effectively ended bank runs. Part of the effectiveness of deposit insurance is depositor preference regimes. Depositor preference means that the first claim (after administrative costs) on bank assets is depositors--even uninsured depositors. This bedrock principle of safe and sound deposit insurance  diminishes incentives for even uninsured depositors to panic and withdraw their funds from banks. The megabanks derivatives activities have ended depositor preference by distorting law and regulation and giving first claim on megabank assets to derivatives counterparties. Specifically, as Mark Roe writes here (and the FDIC apparently concurs here):

"derivative counterparties unlike most other. . .creditors, can seize and immediately liquidate collateral, readily net out gains and losses in their dealings with the bankrupt, terminate their contracts with the bankrupt, and keep both preferential eve-of-bankruptcy payments and fraudulent conveyances they obtained from the debtor, all in ways that favor them over the bankrupt’s other creditors. Their right to jump to the head of the bankruptcy repayment line, in ways that even ordinary secured creditors cannot, weakens their incentives for market discipline in managing their dealings with the debtor because the rules reduce their concern for the risk of counterparty failure and bankruptcy."

Basically, this means that derivatives creditors get an FDIC super-priority that no other bank creditor gets--not even a depositor. This super priority risks bank runs by large uninsured depositors who will justifiably flee the megabanks at the first sign of trouble. What will remain of a bank's assets once the derivatives creditors have grabbed all the collateral for their derivative claims?

All of the four above points show that derivatives exist largely as a function of government indulgences and subsidies that have nearly zero legitimate policy bases. It is yet another testament of the triumph of power over policy.

This is utter foolishness as it ignores basic financial history, further subsidizes zero sum transactions that threaten financial stability, and places the economic interests of a handful of financial elites above 300 million Americans and the entire global economy.

In fact, I can think of nothing positive to say about the legal and regulatory frameworks applicable today to derivatives and TBTF banks, as I previously argued, here, here, here, here, and here.

Thursday, July 18, 2013

More Cowbell . . . .

Jeffrey Skilling mug shot
Public Domain
Interesting and relevant corporate news over the past several days.  In catching up on recent stories pertinent to issues of justice, the following seem particularly relevant in connection with previous posts on the Corporate Justice Blog:

Enron's Skilling to Leave Prison in 2017 as Sentence Cut:  "Former Enron Corp. Chief Executive Officer Jeffrey Skilling, who spearheaded the fraud that destroyed the world’s largest energy trader, will leave prison in 2017 after his sentence was reduced to 14 years from 24.  U.S. District Judge Sim Lake III in Houston yesterday approved the terms of the deal made between prosecutors and Skilling, who appeared at the hearing dressed in prison-issued green clothes and wearing handcuffs that were removed in court. In exchange for a shorter sentence, Skilling, 59, agreed to forfeit $45 million, drop his bid for a new trial and end litigation over his 2006 conviction and sentence. The former CEO’s prison term was already set to be reduced by nine years, thanks to a 2011 appellate-court ruling that sentencing guidelines were incorrectly applied in his case."

 Wall Street's "Fabulous Fab" Heads to Trial:  "The trial of the infamous ex-Goldman Sachs trader Fabrice 'Fabulous Fab' Tourre, which start[ed] Monday [July 15, 2013], could put a face on the type of Wall Street recklessness that imploded the housing market and almost sank the economy five years ago. . . .  If Tourre is found liable, he could face a hefty fine from the SEC and be barred from working in the financial industry. 'The SEC can take a real bite out of you . . . The sky's the limit in terms of the monetary penalties.'  The SEC has filed civil charges against Tourre and is taking him to trial largely based on e-mail evidence. The SEC alleges that, based on the messages, Tourre knew he was selling compromised investments - packages of real estate debt that had been expected to fail and were being shorted by hedge fund firm Paulson & Co."

States Promise Quick Action on Election Laws After Ruling on Voting Rights Act:  "Across the South, Republicans are working to take advantage of a new political landscape after a divided U.S. Supreme Court freed all or part of 15 states, many of them in the old Confederacy, from having to ask Washington's permission before changing election procedures in jurisdictions with histories of discrimination.  After the high court announced its momentous ruling . . . officials in Texas and Mississippi pledged to immediately implement laws requiring voters to show photo identification before getting a ballot. North Carolina Republicans promised they would quickly try to adopt a similar law. Florida now appears free to set its early voting hours however Gov. Rick Scott and the GOP Legislature please. And Georgia's most populous county likely will use county commission districts that Republican state legislators drew over the objections of local Democrats."

Marissa Mayer
courtesy of Wikimedia Commons/Giorgio Montersino

How One Year of Marissa Mayer has Changed Yahoo:  "Yahoo CEO Marissa Mayer likes to shop.  During Mayer's one-year tenure -- her start date was a year ago Wednesday [July 17, 2013] -- Yahoo has bought an incredible 16 startups. And she didn't even start the buying spree until she'd been CEO for three months. Since then Yahoo's acquisitions have been made at a breakneck pace, with the company sometimes announcing two purchases in a single day, or six over the course of a month.  'It is just astounding how truly active Yahoo has been on the M&A front,' said S&P Capital equity analyst Scott Kessler. 'They're mostly buying very small companies, but still -- I don't know that any other company has matched this pace of buying.'"


Monday, July 15, 2013

"Professor Calls War on Drugs an 'Abomination'"

The War on Drugs has been waged in a wildly discriminatory manner.  The decision to wage the war on drugs in urban and poor communities from its inception was a conscious decision made by lawmakers and politicians from the very early days of the so called "war."  Incarceration rates of African American and Latino citizens are massively out of proportion to their population rates, despite overwhelming evidence that Americans use drugs in very similar percentages across all races.  Two explanations for this disproportion in connection with drug arrests are first, that it is much easier to incarcerate citizens from poor and powerless communities, making it true that urban and poor communities are hyper-policed, while frat houses, suburban communities, and wealthy neighborhoods, where drug use is just as prevalent, are rarely policed; and second, that politicians and lawmakers deliberately waged the War on Drugs in urban and poor communities to re-subordinate minority citizens, in light of their gains from the Civil Rights movement, particularly passage of the Civil Rights Act and the Voting Rights Act (recall that President Nixon declared the War on Drugs in the early 1970s, and President Reagan federalized the war in the early 1980s, just a few years after real political and social gains were made by minority citizens).


cummings speaks to the Unitarian Universalist congregation
One of the primary reasons it has been so difficult to end the failed War on Drugs, is that corporate interests and profit increase are now deeply entangled and entrenched in the United States prison industry.  The advent of the private prison corporation in the late 1970s with the introduction of the Corrections Corporation of America in Tennessee, now ensures that dozens of millions of dollars are spent annually by private prison executives to lobby aggressively for increases in private prison facilities, increases in crimes that lead to jail time, increases in length of sentences, and increasing incarceration rates of American citizens and illegal residents.

Corporate interests are now energized by the profit potential of increasing incarceration in the United States.  Perverse incentives are innumerable now for the private prison executive.  Immoral motives, attendant stereotypes and damaging public perceptions have grown out resulting in outcomes such as the "Kids for Cash" scandal in Pennsylvania (where sitting state judges received bribes and kickbacks for every juvenile that they sentenced to jail time in a private juvenile detention center); the horrible Trayvon Martin murder and acquittal (where an innocent, random African American boy was profiled as a "punk," and "suspicous" likely drug dealer by a neighborhood watch volunteer who followed, shot and killed the youth); the SB-1070 "show your papers" law in Arizona (that was drafted by the private prison lobby and handed over to willing legislatures who introduced the law verbatim).  Terrible outcomes motivated by immoral and perverse incentives are the cognizable result of the private prison industry.

Saturday, July 13, 2013

Deflation Everywhere?

FRED Graph
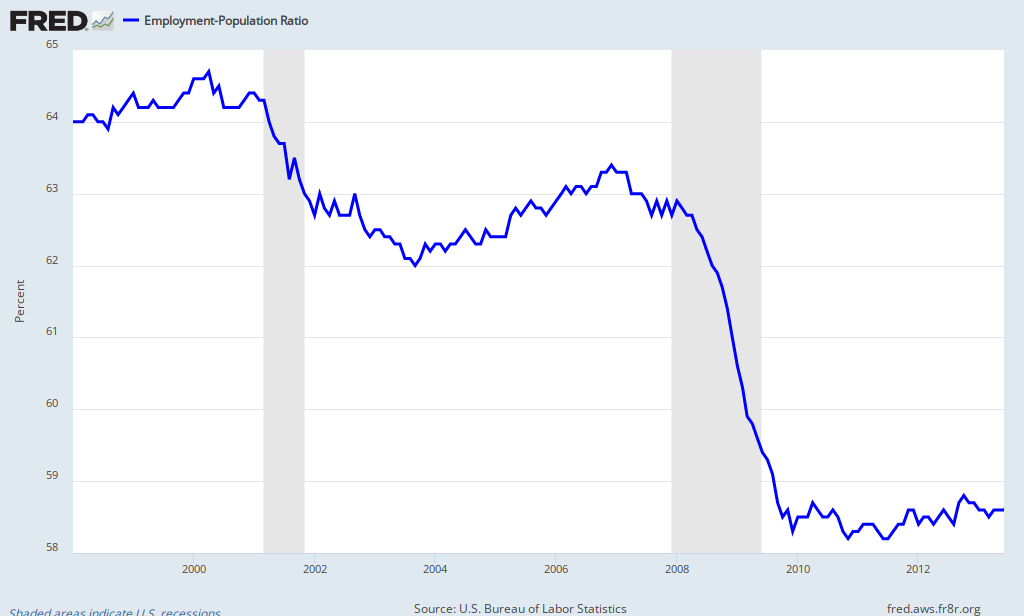
We all remember the unpleasant days of late 2008. As evident from the above, financial instability led to a solid two years of job losses. In terms of the broadest measure of employment, the ratio of the population that is employed, there has been little improvement since 2009 . Indeed, employment in America contracted for the last 13 years. We never recovered from the 2001 recession, much less the Great Recession of 2007-09. That takes a toll on an economy as fewer jobs means less demand and less opportunity for innovation (which is the only true source of sustainable growth). It is also fundamentally deflationary as workers cannot demand wage increases, breaking the possibility of an inflationary spiral.

In fact, while US productivity soared, "[w]ages have fallen to a record low as a share of America’s gross domestic product. Until 1975, wages nearly always accounted for more than 50 percent of the nation’s G.D.P., but last year wages fell to a record low of 43.5 percent. Since 2001, when the wage share was 49 percent, there has been a steep slide." This basic loss of buying power (relative to output) for workers combined with loss of bargaining power for wage increases creates a powerful deflationary bias in our economy. Just look:


As The Economist notes: "The core PCE number (personal consumption expenditure deflator) is only 1% - a modern low - and the Dallas Fed, which uses a trimmed mean number (eliminating the outliers), actually recorded a small fall in the latest numbers (see the definition here)."

In the face of all this evidence of deflationary forces, the US now assumes a contractionary fiscal policy due to the mindless sequestration and the Fed is talking about tapering-off its monetary stimulus. Both fiscal and monetary policy now look strongly contractionary in the US.

Economic stagnation looks worse in other parts of the world. In the Eurozone unemployment recently reached an all time high of 12.2 percent which flirts with outright depression. Some areas of the Eurozone are already in deep depression with only bleak prospects ahead. In Spain, unemployment hovers at 27 percent. I blogged recently about the biggest basket case in Europe (Italy) but in fact austerity has failed everywhere and southern European debt burdens have increased not decreased as the eurocrats promised. Politically, disruptions could erupt at any minute across the Eurozone, as Spain is reportedly in a pre-revolutionary state and even France is fraying. Just this week Portuguese debt yields spiked to highs not seen for months; this signals real problems ahead in the Eurozone.

Then there is China. The world's second largest economy is clearly slowing down. China recently experienced a dramatic credit crunch that suggests its banking sector is overextended. Some experts see major problems ahead. At the very least, China is losing steam and cannot support global growth anytime soon.

“Japan’s economy is starting to recover moderately.” But, the problem here is that Japan is already in a deflationary spiral and prices only stopped falling in May. This progress all comes at the expense of the rest of the world which suffers as Japan drives down the value of the Yen and exports deflation. It is not internally generated growth as the rest of the world recognizes. As the Yen declines (20 percent in just 8 months), Japan can effectively flood the world with cheap goods. As one expert states: "Forget cars, Nintendo machines or anime. Japan’s biggest export right now is deflation."

So, looking at all the world's biggest economies, it is hard to remember more deflationary pressures than right now. Certainly, not since the summer of 2008 did the global economy seem more vulnerable to a major shock.

Friday, July 12, 2013

Is Italy the Next Cyprus?


 http://image1.frequency.com/uri/w234_h132_ctrim_ll/_/item/1/0/4/9/MORE_BANK_RUNS_COMING_ACROSS_EUROPE_104945338_thumbnail.jpg
S&P downgraded Italy earlier this week.
European financial experts project that Italy will need a financial bailout within six months. Italy has about $2.5 trillion in outstanding debt--meaning that any problems with a possible default will send a tsunami through global financial markets. So how likely is an Italian credit crisis?

Consider the following facts: Italy's economy has contracted for 7 straight quarters; industrial production has fallen for 15 straight months; since 2008 factory output has plunged 25 percent; poverty has doubled; and its debt has soared to 130 percent of GDP. Austerity has increased Italy's debt load, crashed its economy and spawned immense suffering among the Italian people. Or, as economics Professor Krugman puts it: austerity has been a "disastrous failure." He is not the only Nobel laureate who thinks that. Indeed, the stability of the government itself has been compromised and the high unemployment rate for Italian youth (38.5 percent) promises more political unrest.

Italy is also way behind on its bills and does not have the funds to pay. This in turn is leading to mass bankruptcies of Italian businesses.

A default sure seems credible from my view. What does that look like?

The place to start for that question is Cyprus. This was the most recent and most radical bailout by the EU, the IMF and ECB. Basically, this trioka of eurocrats deemed that depositors must pay and pay big for the errant ways of Cypriot banks. Thus, uninsured depositors were forced to become shareholders of insolvent banks (up to 60 percent of the amount that exceeds $130,000) and had most of the rest of their deposits frozen. Even insured deposits are subject to capital controls that have been in place since late March and will not be lifted until at least September: this means that all depositors can only withdraw about $400 per day, cannot cash checks, and face monthly limits on transfers out of the country. Who needs that noise, and how does one know it will not worsen?

Cyprus is the new "model" for Eurozone bailouts. Deposit confiscation, limited only by what the eurocrats think the government can get away with.

Given these facts who in their right mind would leave any money in Italian banks? And, if Italy proved too big to bail out, why would anyone leave money in Spanish, Portugese, and Greek banks? Under these circumstances Eurozone bank runs on a massive scale seem almost inevitable and certainly rational.

Saturday, July 6, 2013

Reflections on the Fourth of July 2013

I watched many fireworks this past few days. I also ate well.

In between, I thought hard about this celebration of America. In particular I thought very hard about the meaning of Gettysburg, the enormous Civil War battle that occurred 150 years ago in Pennsylvania (1 July 1863 to 3 July 1863).

Here are my conclusions, for better or worse:

1) The United States is Revolution Proof

Basically, a strong majority will at least appear to prevail in the political arena and will thus find accommodation within our Constitutional system. A determined and organized minority may revolt--as the Confederacy did in 1861--but they will lose as they will be out-manned and out-gunned given the position of the President as Commander in Chief of the Armed Forces.

2) The South Never Stood a Chance

Gettysburg marks the high tide of the Confederacy. By all accounts, General Lee desperately needed a complete victory so he could march on Washington and seek a negotiated peace. Despite a long string of victories Lee understood that the South was out of troops and munitions and the North was nearly inexhaustible. This meant he needed to gamble and seize the offensive. Gettysburg was the logical conclusion of that gamble. The Union held dug-in positions on the high ground. Lee's attack resulted in the loss of over 1/3 of his Army which rendered victory in the ensuing war of attrition impossible. It is hard to imagine a stronger rebellion than the Confederacy--yet, it failed.

3) Revolution by Other Means is Similarly Impossible

In some nations, protests, coups and other mechanisms have resulted in regime change. But, not in the USA. In the US superior leaders are generally co-opted into the system. Because the US has long been the land of opportunity (albeit less so in recent years) the most talented in the system soon become invested in the system. People with IRA accounts and 30 year mortgages are not likely to revolt.


4) Those Seeking Change Must Work Within the US Constitution and Under Law

All of this precludes radical change in the US. Only change within the existing legal framework is possible and desirable. Overall, the historical outcomes of revolutions are mixed at best. It is hard to find a successful rebellion in a functioning republic or democracy.

The upshot of this is that any talk of violent armed revolt is nonsense. The US military is so advanced today that no amount of small arms can match it.

Those interested in change should look to history to learn how legal and regulatory reforms took root in the past. Similarly, one can analyze law and determine mechanisms available for durable reform. Reformers can also study political contexts that support reform efforts and try to propose reforms that fit with a given political context. This is the only path for reform in the US right now and those offering more radical paths are destined to fail and even further entrench the status quo.

Wednesday, July 3, 2013

Critical Race Theory: The Cutting Edge

Professors Richard Delgado and Jean Stefancik have just released the third edition of their seminal compilation Critical Race Theory: The Cutting Edge.  This book traces the evolution of Critical Race Theory and examines wide ranging topics, including economics, class, and wealth, critiquing and offering solutions through critical analysis. 

According to the Temple University Press: "Critical Race Theory has become a dynamic, eclectic, and growing movement in the study of law. With this third edition of Critical Race Theory, editors Richard Delgado and Jean Stefancic have created a reader for the twenty-first century—one that shakes up the legal academy, questions comfortable liberal premises, and leads the search for new ways of thinking about our nation's most intractable, and insoluble, problem—race.

The contributions, from a stellar roster of established and
emerging scholars, address new topics, such as intersectionality and black men on the "down low."  Essays also confront much-discussed issues of discrimination, workplace dynamics, affirmative action, and sexual politics. Also new to this volume are updated section introductions, author notes, questions for discussion, and reading lists for each unit. The volume also covers the spread of the movement to other disciplines such as education.

Offering a comprehensive and stimulating snapshot of current race jurisprudence and thought, this new edition of Critical Race Theory is essential for those interested in law, the multiculturalism movement, political science, education, and critical thought."

Thursday, June 27, 2013

The Crippling of the Voting Rights Act

Professor Atiba Ellis
Steven Ramirez posted yesterday on the Supreme Court's tone deaf holding in Shelby County v. Holder where the Court held that section 4 of the Voting Rights Act was unconstitutional. Atiba Ellis weighs in today on the ACS Blog calling the Supreme Court's decision a "crippling of the Voting Rights Act."

According to Professor Ellis:  "In Shelby County, AL v. Holder, the Supreme Court, in a 5-4 decision split on ideological lines, declared unconstitutional the formula used under the Voting Rights Act of 1965 to determine which states and localities must receive pre-approval of their voting rights laws. This decision, which effectively ends the preclearance practice meant to preserve minority voting rights, will transform the right to vote for years to come. Once again, relying on the myth of racial progress, the Supreme Court failed to confront the racial balkanization in voting that exists, and it ultimately crippled the role that Voting Rights Act has in limiting it. . . ."

Professor Ellis goes on to critique the key analytical premise relied upon by Chief Justice Roberts:  "The key premise of the Shelby County opinion is that the covered jurisdictions – mainly the ex-Confederate South – have changed so sufficiently that the government must reconsider selective preclearance enforcement of race-conscious remedies. The message of the Roberts opinion (and the Thomas concurrence) is that coverage formulas rooted to a past of racial discrimination in voting ignores racial progress.  Indeed, Roberts implied that to hold to such formulas amounts to punishment of the states covered for their racial history. (Slip op. at 20).
 
The majority’s analysis is incomplete and unpersuasive on this key issue. Indeed, it sidesteps the arguments put forward by both sides concerning the degree of progress as “debatable” (Slip op. at 21) rather than grapple with exactly how much progress we have made to racial political equality.  Instead, the majority simply asserted (again and again) that Congress had no basis in current political reality to rely on the current coverage formula.  Id. Rather than account for the varied forms of second-generation voter intimidation as evidence on which Congress could have based its findings, the majority suggests that increased voter participation demonstrates enough progress towards racial political equality to effectively scuttle Section Five.

As I argued before concerning the Shelby County case, this incomplete picture of racial triumph ignores the political realities of modern voter suppression tactics and their racial impact. Relying on this ideological view causes the majority to fall into the trap of wanting to believe that the markers of progress represent success rather than confronting the far more complex reality.  Moreover, without Section Five’s moderating influence and example, the voting wars will proceed unchecked – and we as a country may very well see the erosion of the right to vote. The consequences of this premature post-racial decision will likely define – negatively -- the scope of voting rights for the 21st century."

Professor Ellis succinctly describes the blinders that the majority opinion justices willingly wore when considering the Shelby County case.  In reality, voting as a constitutional right should be openly encouraged of all citizens.  In Brazil, voting is required with a Brazilian citizen paying a small penalty/fee if he or she fails to cast a ballot.  Why is so much energy being put forth in the United States to actually restrict voting and access to the ballot box?  Professor Ramirez provides some answers to that question in yesterday's post, calling GOP efforts to restrict voting an unconscionable "effort to disenfranchise voters of color nationwide."  Voter fraud is pretext.  Laws on the books appropriately punish those rare cases where individuals attempt to engage in voter fraud.  Instances of voting fraud are miniscule.  Efforts to dramatically restrict the rights of citizens to vote through voter ID laws, restricted early voting, and closing the number of polling places in large communities are all efforts to disenfranchise 21st century voters.  This point escapes the five member majority of the Shelby County opinion (or they are ostriches as Justice Ginsburg argues).

Wednesday, June 26, 2013

MARCH ON WASHINGTON!

File:Lyndon Johnson and Martin Luther King, Jr. - Voting Rights Act.jpg 

Yesterday, by a 5-4 vote, the Supreme Court effectively eviscerated the Voting Rights Act of 1965. Although originally signed into law by President Lyndon Johnson, the Act was extended by President Bush in 2006, after clearing the Senate 98-0. The New York Times (along with other media outlets) condemned the opinion as "intellectually dishonest" while more conservative voices found it "defensible."

Congress enacted the Voting Rights Act under the Fifteenth Amendment. That Amendment gives express and broad power to Congress to secure voting rights of communities of color. It only requires any such legislation be "appropriate." As Justice Ginsburg stated in her blistering dissent: "When confronting the most constitutionally invidious form of discrimination, and the most fundamental right in our democratic system, Congress' power to act is at its height." (slip op., dissent at 8). Moreover, Justice Ginsburg also noted that the Constitution always limited state sovereignty regarding elections under the elections clause.

No observer can possibly claim that racial discrimination in voting is over. Indeed, Justice Roberts, who wrote the majority opinion, admits that "voting discrimination still exists." Further, the Voting Rights Act effectively operated for decades to reduce disparities in voter registration. (slip op. at 15). Again, Justice Roberts admits this.

But instead of leaving effective and necessary legislation in place, Justice Roberts uses the success of the Act to claim that the Act is not based sufficiently on "current conditions." In fact, Justice Roberts seemingly chides Congress for not "updating" the Act.

That is not an appropriate level of deference for voting rights legislation under the Fifteenth Amendent. Judicial review does not give the Court license to second guess our elected officials. This is judicial activism running riot. Tellingly, Justice Roberts cites to no precedent overturning Congressional voting rights legislation under the Fifteenth Amendment.

Some claim that this Court simply acts in a brazenly partisan way. While I hesitate to reach that conclusion, it seems clear that the Supreme Court fears the voting power of communities of color. First, they dare not overturn affirmative action (just yet). Then, they nullify the Voting Rights Act of 1965. The majority of the Court acts as though the voting power of communities of color is the problem. The Court has certainly given a green light to GOP efforts to disenfranchise voters of color nationwide, as evidenced here, here, here and here.

So, we have little option, as those resistant to the efforts of entrenched power to perpetuate injustice illegitimately, but to march on Washington. There is already a march organized for August 24th to commemorate Martin Luther King's I Have a Dream speech of 50 years ago.  This march forms an ideal platform to demand a new voting rights act now.

Given the nature of efforts to disenfranchise minority voters perhaps a new Voting Rights Act of 1965 could emerge as an even stronger source of protection for voting rights across the entire nation. If the Court sought to curb the voting power of voters of color, this decision could easily backfire. Indeed, efforts to disenfranchise minority votes seem to increase turnout.

The five justices in the majority, as Republican appointees, certainly belie any supposed GOP effort toward greater inclusivity.
 
See you in Washington!

Monday, June 24, 2013

AFFIRMATIVE ACTION AFFIRMED

The Supreme Court today released its awaited affirmative action decision.

The full text of the opinion in Fisher v. University of Texas is available here. Essentially, the Court remanded to the Fifth Circuit and directed the lower courts to apply its affirmative action precedents in Grutter and Bakke.

I have little to add to my first post on this case: Fisher v. Texas: Affirmative Action for Whites Only? I do however wish to highlight that this case seems to obviously reflect the new political realities of an increasingly diverse nation. As such, conservatives would be well advised to embrace this outcome as a de minimis step for relieving continued racial oppression in America.

For example, there is this grim reality for children of color in America:

 
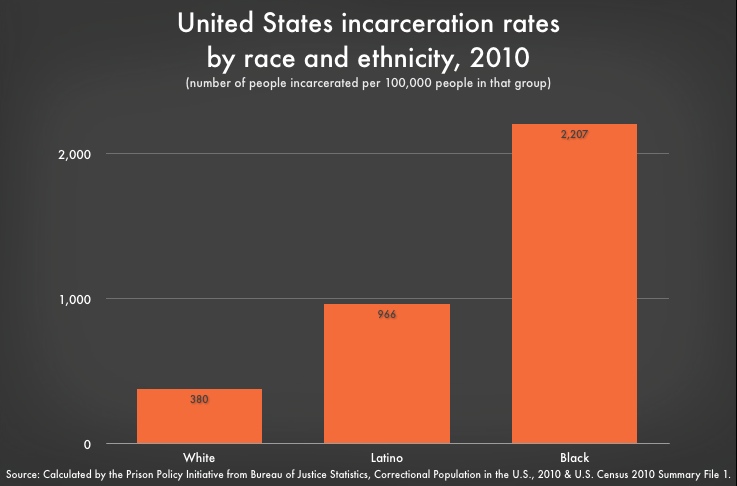
Or, consider this obscene reality for incarceration rates in America:

incarceration rates by race graph
Facts are stubborn things and conservatives ought not to ignore these morally reprehensible racial disparities. If not swayed by morality, let them be swayed by political reality.

Thursday, June 13, 2013

Charitable Giving?

Corporations are legally permitted to expend general treasury funds for charitable purposes.  Indeed, corporations are encouraged to contribute to charities in order to improve the communities in which they do business and to support the consumers that purchase their products or use their services.  State rules place parameters around the amount of money that can be allocated from corporate coffers to charitable entities with most rules allowing contributions that are reasonable in amount, related to a corporate purpose, and not distributed to "pet" charities.  With corporations now stepping into the giving role that large philanthropic families played in the 19th and 20th centuries (like the Mellon family, the Rockefeller family, etc.), and with charities relying more heavily than ever on corporate gifts, what are we to make of news today that dozens of charities are little more than scams initiated by individuals seeking easy windfalls?

CNN, together with the Tampa Bay Times and the Center for Investigative Reporting, released a stunning report today indicating that hundreds, if not thousands of charities are siphoning millions of dollars from charitable givers and enriching charity founders and executives and for-profit companies that are paid to solicit the charitable gifts.  This report indicates that thousands of charities pay for-profit vendors to raise their donations, sometimes spending more than 90% of the contributions on soliciting more contributions.  CNN reports that the worst charity investigated was the Kids Wish Network:

"Every year, Kids Wish Network raises millions of dollars in donations in the name of dying children and their families.  Every year, it spends less than 3 cents on the dollar helping kids.  Most of the rest gets diverted to enrich the charity's operators and the for-profit companies Kids Wish hires to drum up donations.  In the past decade alone, Kids Wish has channeled nearly $110 million donated for sick children to its corporate solicitors. An additional $4.8 million has gone to pay the charity's founder and his own consulting firms.  No charity in the nation has siphoned more money away from the needy over a longer period of time.  

But Kids Wish is not an isolated case, a yearlong investigation by the Tampa Bay Times and The Center for Investigative Reporting has found.  Using state and federal records, the Times and CIR identified nearly 6,000 charities that have chosen to pay for-profit companies to raise their donations.  Then reporters took an unprecedented look back to zero in on the 50 worst - based on the money they diverted to boiler room operators and other solicitors over a decade.  These nonprofits adopt popular causes or mimic well-known charity names that fool donors. Then they rake in cash, year after year. The nation's 50 worst charities have paid their solicitors nearly $1 billion over the past 10 years that could have gone to charitable works."

The Kids Wish Network is not alone.  This investigative report listed the 50 worst charities.  Below is a chart listing the top ten worst charities ranked by money spent on soliciting costs versus money spent on direct cash aid.

Are publicly traded corporations engaging in appropriate due diligence before spending general treasury funds on charitable contributions?  The report above indicates that there is an urgent need to engage in such diligence.

The 50 worst, ranked by money blown on soliciting costs

Totals from the latest 10 years of available federal tax filings
RankCharity nameTotal raised by solicitorsPaid to solicitors% spent on direct cash aid
1 Kids Wish Network $127.8 million $109.8 million 2.5%
2 Cancer Fund of America $98.0 million $80.4 million 0.9%
3 Children's Wish Foundation International $96.8 million $63.6 million 10.8%
4 American Breast Cancer Foundation $80.8 million $59.8 million 5.3%
5 Firefighters Charitable Foundation $63.8 million $54.7 million 8.4%
6 Breast Cancer Relief Foundation $63.9 million $44.8 million 2.2%
7 International Union of Police Associations, AFL-CIO $57.2 million $41.4 million 0.5%
8 National Veterans Service Fund $70.2 million $36.9 million 7.8%
9 American Association of State Troopers $45.0 million $36.0 million 8.6%
10 Children's Cancer Fund of America $37.5 million $29.2 million 5.3%

Thursday, June 6, 2013

The Sordid Private Prison Corporation Agenda

"Kids for Cash" Judge Mark Ciavarella
News out of the United States this week in connection with the debacle that is the for-profit private prison corporation regime borders on deprave.  That the privatization of the prison industry in the U.S. (and abroad) is not now considered an epic failure is mystifying.  In Pennsylvania, Mark Ciavarella, Jr., the former juvenile court judge that orchestrated the "Kids for Cash" scandal, was formally sentenced to 28 years in prison for his role in sending children to jail in return for cash payments (the Third Circuit Court of Appeals upheld the sentence from his 2011 trial).  Ciavarella was found guilty in 2011 of "engaging in a pattern of racketeering and participating in a racketeering conspiracy through his receipt and transfer of $997,600 from individuals associated with the juvenile detention centers."  Ciavarella and former Judge Michael Conahan were both accused of sending children to private juvenile detention facilities, in Luzerne County, PA, often in violation of the kids' constitutional rights, in return for bribes and kickbacks from private prison owner Robert Mericle for the number of children that they sentenced to spend time in the Mericle-built private juvenile facilities.  Conahan pled guilty to racketeering in 2010, while Ciavarella cavalierly battled the indictment claiming that he received only a "finders fee" for assisting in the construction of the private prison facility.

As reported in 2011 by the Christian Science Monitor, the jury found Ciavarella guilty on 12 of 39 counts in his indictment. Aside from racketeering, he "was also convicted of failing to record the secret payments on judicial financial disclosure forms from 2004 to 2007, and for filing false tax returns for those same years. In addition, the jury found him guilty of engaging in a money-laundering conspiracy to conceal the payments."

The perverse incentives that attach when private corporations seek to control a public function like crime and punishment, including sentencing and imprisonment, literally overwhelms both judges and corporate executives. That a private prison company would actually bribe judges to fill their prisons is appalling.  Just as outrageous is that judges would, without remorse, destroy the lives of young kids by imprisoning them for minor crimes or misbehaviors, in order to receive bribes that the private industry seems more than willing to pay.

GEO Group Headquarters in Florida
Meanwhile, the GEO Group, Inc., one of the nation's largest private prison companies, has been lying to investors and the general public. The mantra of private prison companies is that they "do no harm" as they simply run prisons more efficiently and for lower cost than government can.  In repeating this mantra, the GEO Group and the Corrections Corporation of America (CCA) routinely claim that they do not seek to influence legislatures or lobby for longer sentences, for greater prison time or for the expansion of crimes that will ultimately lead to a stronger flow of prisoners into their prison beds, including claims that they are not involved in the criminalization of immigration.  This however, is reportedly not true.  Not only is there emerging evidence that private prisons run less efficiently and at greater cost than those run by states and municipalities, but GEO Group's public disclosures this year admitted to paying millions of dollars to lobbyists that are seeking to influence immigration policy by sending illegal immigrants into the private prisons.

The Nation reports:  "Earlier this year, one of the largest private prison corporations in the country sent out a statement to reporters claiming that it would not lobby in any way over the immigration reform debate. A new disclosure shows that the company, the Boca Raton–based Geo Group, has in fact paid an 'elite team of federal lobbyists' to influence the comprehensive immigration reform legislation making its way through Congress. . . .

In February and March, Pablo Paez, the Geo Group’s vice president of corporate relations, told media outlets, including the Financial Times and The Nation, that his firm would steer clear of immigration reform politics. . . . 'The GEO Group has never directly or indirectly lobbied to influence immigration policy. We have not discussed any immigration reform related matters with any members of Congress, and we will not participate in the current immigration reform debate.'

Geo Group’s quarterly lobbying disclosure tells a different story. A disclosure filed in April shows that the company turned to Navigators Global to lobby both houses of Congress on 'issues related to comprehensive immigration reform.' Navigators Global, a corporate government affairs firm founded by several Republican aides, has been retained by the Geo Group since 2011 . . . ."

The private prison industry is sordid, evidenced by judicial bribery and lying to investors and the public at large.  How long will we stand for this debauchery?

Tuesday, May 14, 2013

JP Morgan, Again?


Once again, JP Morgan Chase finds itself at the center of controversy.  Casual Wall Street observers must be asking themselves, "will these bankers never learn"?  This time government regulators are accusing the investment banking giant of illegally manipulating energy prices in order to drive up revenue for themselves and investors.  Regulators cite to a document indicating knowledge and approval of bank executives of schemes carried out by a group of energy traders in Houston. According to DealBook:

"Government investigators have found that JPMorgan Chase devised 'manipulative schemes' that transformed 'money-losing power plants into powerful profit centers,' and that one of its most senior executives gave 'false and misleading statements' under oath.

The findings appear in a confidential government document, reviewed by The New York Times, that was sent to the bank in March, warning of a potential crackdown by the regulator of the nation’s energy markets."